The Reserve Bank of India (RBI) has endorsed the introduction of a Merchant Discount Rate (MDR) on UPI transactions exceeding Rs 2,000, effective October 15. This move, which levies a 0.4 per cent fee on merchant payments above the threshold, aims to bolster the long-term sustainability and growth of India's digital payments ecosystem. The RBI clarified that person-to-person (P2P) transactions and small person-to-merchant (P2M) payments below Rs 2,000 will remain free for users, ensuring no direct charge on customers.
The Indian government has introduced a 0.4 per cent Merchant Discount Rate (MDR) on UPI payments exceeding Rs 2,000 made to merchants, effective from October 15, with a comprehensive framework set to take full effect by October 15, 2026. This policy aims to regulate transaction fees while protecting small merchants and person-to-person transactions.

The Indian government has introduced a 0.4% Merchant Discount Rate (MDR) on UPI person-to-merchant (P2M) transactions exceeding Rs 2,000, effective October 15. This move ends nearly six years of fully free UPI payments, though person-to-person (P2P) transfers and small P2M payments remain free. The charges aim to bolster investment in UPI infrastructure, with specific exemptions and caps for essential sectors.
Fintech giant PhonePe has launched 'PhonePe UPI 123Pay', a new service enabling UPI transactions for feature phone users without requiring an internet connection. This initiative aims to bring digital payment capabilities to over 200 million feature phone users, promoting financial inclusion across India.
The Indian government has introduced a 0.4% transaction fee on Unified Payments Interface (UPI) payments exceeding Rs 2,000 for merchants, effective October 15, marking the end of nearly six years of free service. Person-to-person transfers and small-value transactions below Rs 2,000 remain free. The new Merchant Discount Rate (MDR) is capped at Rs 300 for transactions above Rs 75,000, with differentiated rates for essential sectors and investments, and safeguards to prevent costs from being passed to consumers.
Fintech company BharatPe has expressed strong support for the government's new Merchant Discount Rate (MDR) framework for UPI merchant transactions, which introduces a 0.4% fee on transfers exceeding Rs 2,000. The company explicitly distanced itself from critical remarks made by its former co-founder Ashneer Grover, clarifying that his views do not represent BharatPe's stance. BharatPe CEO Nalin Negi highlighted that the framework aims to strengthen digital payment economics, protect consumers and small merchants, and expand adoption in underserved markets, with most transactions remaining unaffected.
BJD chief Naveen Patnaik has voiced concerns over the Centre's decision to introduce Merchant Discount Rate (MDR) charges on UPI transactions above Rs 2,000 from October 15, urging protection for small traders and common people. This move has sparked a political debate, with the BJP defending the charges as beneficial for digital infrastructure and largely not impacting consumers, while the Congress and traders' associations criticise it as an additional burden.
India's UPI system continues its rapid growth, dominating retail payments. Recent amendments to the Payment and Settlement Systems Act allow for targeted Merchant Discount Rates (MDR) on high-value merchant transactions, aiming to create a self-sustaining revenue model for the ecosystem while keeping P2P and low-value payments free. This move could generate significant revenue and encourage ecosystem participation.
The National Payments Corporation of India (NPCI) stated that the Merchant Discount Rate (MDR) "is distributed only amongst the UPI ecosystem, to further invest into infrastructure resilience, innovation, cybersecurity (protecting the UPI infrastructure with banks and non-banks) and customer service."

The government is introducing a 0.4% Merchant Discount Rate (MDR) on UPI person-to-merchant payments above Rs 2,000, effective October 15. This move ends the zero-MDR regime, aiming to fund UPI infrastructure and sustainability, as the previous government subsidy was insufficient to cover operational costs. Payments between individuals and most everyday merchant transactions will remain free.
The BJP has accused the Congress of spreading "fake news" regarding UPI transaction charges, asserting that the government has clarified that consumers will not be levied merchant discount rate (MDR) charges. This comes after the Congress criticised a government notification, alleging it paves the way for imposing fees on UPI transactions. The BJP has strongly refuted these claims, highlighting that most UPI transactions remain free and the government provides incentives to maintain a charge-free ecosystem for users.
Unified Payments Interface (UPI) transactions in India reached Rs 29.8 lakh crore in August, approaching record levels. Volume also hit a new high of 24.51 billion transactions, driven by festive activities like Raksha Bandhan. The digital payment system continues its rapid growth, expanding its global presence to 11 countries, with further growth anticipated during the upcoming festive season and new use cases like credit on UPI.
India's Unified Payments Interface (UPI) recorded an unprecedented 24.51 billion transactions valued at Rs 29.8 lakh crore in August, largely propelled by the Raksha Bandhan festival. This surge marks a 22% annual increase in volume and 20% in value, highlighting the expanding reach and depth of the UPI ecosystem. Experts anticipate further growth during the upcoming festive season, while UPI's international acceptance now spans 11 countries.
NPCI International Payments Ltd (NIPL) and Maldives Monetary Authority (MMA) have successfully integrated the Maldives' instant payment system 'Favara' with India's Unified Payments Interface (UPI). This enables real-time fund transfers from Maldives to UPI-enabled Indian bank accounts, marking a significant step in cross-border digital financial connectivity and bilateral economic cooperation.
Parliament was informed that UPI has onboarded 55.49 crore users by June 2026, with transactions reaching 24,162 crore in volume and Rs 314 lakh crore in value in FY 2025-26. The platform, operated by NPCI, is expanding internationally through NIPL, facilitating cross-border payments and assisting other nations in building similar systems. Significant efforts are also underway by the Government, RBI, and NPCI to enhance the security and transparency of UPI transactions, including risk-based limits, security frameworks, and public awareness campaigns against cyber-crime.
Currently there are 26 licensed players in the P2P lending sector but only 10-11 are actively operating.
India and Nepal have launched a peer-to-peer (P2P) cross-border remittance mechanism, linking India's UPI with Nepal's NPI. This system allows real-time money transfers via mobile banking, enhancing convenience for travellers and businesses, fostering financial inclusion, and strengthening economic ties between the two nations.

Following a review of peer-to-peer (P2P) platforms, certain issues -- including high non-performing asset levels, significantly high balances in escrow accounts, and non-compliance with net owned fund and disclosure requirements -- came to the RBI's attention.
P2P platforms do not have the safety net. Instead of playing the role of an intermediary, if they run their own balance sheets for safety and growth, it's a recipe for disaster, warns Tamal Bandyopadhyay.
Bad loans in the peer-to-peer (P2P) lending industry more than doubled in financial year 2024 (FY24) to Rs 1,163 crore from Rs 472.1 crore in FY23, said a financial services company on Monday. Non-performing assets (NPAs), as such loans are officially called, were a modest Rs 14.7 crore at the end of FY19 when P2P lending was in its nascent stage, according to Capitalmind Financial Services that accessed data from the Reserve Bank of India (RBI) through a right to information application.
A new report indicates that UPI has become the dominant payment method for lenders, accounting for over 90% of transactions. The report also highlights trends in investment amounts, diversification strategies, and geographic participation in peer-to-peer lending.
Instead of being guided only by returns, investors should also factor in the risks of lending on these platforms.

The Indian government has blocked 300 websites and applications involved in illegal gambling and betting activities, including online sports betting platforms, online casinos, and satta/matka networks, as part of its efforts to create a safe and responsible online gaming ecosystem.

'As banks grapple with risk aversion and savers see an erosion in the value of money, the P2P platform can be a win-win for both borrowers and lenders,' notes Tamal Bandyopadhyay.

Mirroring the traditional hawala system, where money is sent through non-banking channels, this digital version uses the anonymity of unregulated cryptocurrency to erase the financial trail and inject cash into the domestic economy.
Ever wonder how your friends have all the latest music blaring on their iPods while you're still trying to get your hands on the CD? Chances are, they've downloaded them using free P2P (peer-to-peer) file-sharing software.

Nearly 7 out of every 10 P2M UPI transactions take place in high frequency categories like groceries, restaurants, pharmacies, fuel service stations, bakeries and utility services such as electricity, gas, water and sanitation.
Several executives argue that UPI has the potential to grow tenfold, but warn that the absence of a monetisation model risks stagnating the real-time payments system, which has been recording all-time-high transaction volumes every year.
Fintech firm BharatPe is targeting an initial public offering (IPO) in the next 18-24 months with the company expecting profitability at an earnings before interest, taxes, depreciation and ammotisation (Ebitda) level for FY25, chief executive officer (CEO) Nalin Negi said.
The fear of losing purchasing power due to inflation and low-interest rates has led many to explore safe alternatives to fixed deposits with high returns
Non-banking entities such as fintech firms will have to tap into use cases beyond peer-to-peer (P2P) and peer-to-merchant (P2M) transactions to scale up the presence of the retail version of the central bank digital currency (CBDC), which is also known as the e, said industry players. These use cases will enable programmable transactions across domains, including the government's direct benefit transfer (DBT) schemes, with subsidies restricted to specific purposes such as food coupons, hospital bills, fertilisers, pesticides, and cross-border remittances.
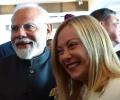
Prime Minister Narendra Modi held a series of bilateral meetings with his global counterparts on the margins of the G7 Summit in Kananaskis, with discussions focusing on a range of issues such as trade, investment, counter-terrorism and global challenges.
The RBI has changed the way it approached supervision in the past. Having seen a couple of collapses in the NBFC sector and the near-collapse of a few banks, it is focusing on regular drills to prevent a fire from breaking out, explains Tamal Bandyopadhyay.
The Fintech Association for Consumer Empowerment (FACE), the only self-regulatory organisation for financial technology/fintech (SRO-FT) companies, is aiming to secure membership from at least 75 per cent of players across all key fintech categories within the next three years, according to a senior executive. The total number of members in the organisation has increased to 110, up from around 60 when it received approval from the Reserve Bank of India (RBI) to operate as an SRO-FT in August.
rediffGURU T S Khurana answers readers' personal income tax queries.
The average value of retail digital payments dropped 48 per cent from Rs 8,769 in March 2021 to Rs 4,560 in March 2024 due to a growing preference to use digital modes of transactions for small value payments, according to the Reserve Bank of India's (RBI) report on the trend and progress of banking in India.
It said two of the key accused were Islamic State of Iraq and Syria radicals, who used fraudulently obtained "Indian SIM cards and Indian bank accounts" besides "various Indian and Bangladeshi Identity documents downloaded from the dark web (which is accessible only through specialised browsers) in carrying out their nefarious activities.
The average ticket size (ATS) of all transactions on United Payments Interface (UPI) in H1 2023 was pegged at Rs 1,604, marking a 10 per cent decline, compared to Rs 1,774 in H1 2022, according to data from Worldline India's Digital Payments Report. The reduction in the overall ATS on UPI is a good sign, suggesting a deeper embedding of UPI as it is being used for smaller or micro-transactions, and the dip is driven by the growth in person-to-merchant (P2M) transactions, the report said. The ATS of P2M transactions dipped 21 per cent from Rs 839 in H1 2022 to Rs 659 in H1 2023.

Mobile wallet adoption is surging in India and swiftly becoming a primary payment option, surpassing traditional methods like cash and cards. Over the next few years, payments via mobile wallets in India are likely to surpass the Rs 531.8 trillion mark in 2028, witnessing a compound annual growth rate (CAGR) of 18.3 per cent between 2024 and 2028, according to GlobalData - a London-based leading data and analytics company. The value of mobile wallet payments in India, as per a GlobalData report, grew at a CAGR of 72.1 per cent between 2019 and 2023 to reach Rs 202.8 trillion ($2.5 trillion) in 2023.

Has Vijay Shekhar Sharma given up on the bank? For now, he seems to be on a save-OCL mission. The bank will face its logical end, observes Tamal Bandopadhyay.
