Corporate India's struggle with subdued revenue and earnings growth persisted in the October-December quarter of 2024-25 (Q3FY25). The combined net sales (gross interest earnings for lenders) of listed companies grew in single digits for the seventh consecutive quarter, while their combined net profit rose by a single digit for the third straight quarter.
Saibaba died at due to gall bladder infection and other complications.
HDFC Bank's January-March quarter result, which came in-line with expectations, failed to enthuse investors. The reason? The management's decision to abstain from providing any specific growth guidance, and analysts' expectations of an arduous road to recovery. Analysts believe the path to normalisation of several growth metrics is unlikely to be a straightforward one, and the road to balance sheet realignment may be long.
It is to be seen if SBI under Setty, who will have a three-year term, can ride the economic cycle to take SBI to new heights, navigating some of these challenges.

Every banker loves the four-letter word Casa as it plays an important role in lowering the cost of deposits. Every bank wants to increase its Casa, as a higher portion of Casa in the overall deposit liability brings down its cost of money, points out Tamal Bandyopadhyay.
Yes Bank on Saturday reported over two-fold jump in standalone net profit at Rs 452 crore for March quarter 2023-24, primarily due to benefits on the provision front. In the year-ago quarter, the bank logged a profit of Rs 202.43 crore. The private sector lender benefitted from write-back on income tax and interest on income tax returns, but the profits were limited by its inability to comply with the mandatory priority sector lending (PSL) requirements, its management said.
Despite steady loan growth, the banking sector is expected to report subdued margins in the quarter ending June 2024 (Q1FY25), driven by high demand for deposits amidst tight liquidity conditions. However, according to Bloomberg analysts, listed banks are forecasted to see a 14.5 per cent year-on-year (Y-o-Y) increase in net profit. Estimates showed that banks' net interest income (NII), and revenues from interest minus interest expenses might grow 11.9 per cent Y-o-Y.

Cholamandalam Investment and Finance's (Chola) share has yielded one of the best returns in the last month. The company has sustained assets under management (AUM) growth at 7 per cent quarter-on-quarter (Q-o-Q), and 35 per cent year-on-year (Y-o-Y) in Q1FY25. Scaling up of new businesses now contributes to 13 per cent of loans (vs 10 per cent in Q1FY24).

Led by Borja Herrera's sensational hat-trick, FC Goa secured their first win of their Indian Super League 2024-25 campaign as they edged past hosts East Bengal 3-2 in Kolkata on Friday.
Treasury gains helped ICICI Bank post a nearly 10 per cent increase in the consolidated net profit for the April-June quarter at Rs 11,696 crore on Saturday. Growth in the core income slowed for the country's second largest private sector lender, but the treasury operations helped it report a 14.62 per cent rise in its post-tax profit at Rs 11,059 crore on a standalone basis. The core net interest income (NII) growth came at a multi quarter low of 7.3 per cent to Rs 19,553 crore for the reporting quarter.
HDFC Bank on Monday reported a consolidated net profit of Rs 16,811 crore for the September quarter, its maiden quarterly earnings announcement after merging parent HDFC with itself. On a standalone basis, the largest private sector lender reported a net profit of Rs 15,976 crore. In the year-ago period, the net profit of the merged entity would have been Rs 11,162 crore on a consolidated level while the same on a standalone basis would have been Rs 10,606 crore.

'If the majority falls short of expectations, it may prompt initial adjustments in investor sentiment.'
State Bank of India's earnings growth may turn lacklustre in the near-term, warn analysts. This, they said, could be due to margin compression and likely lower fee income over the next one year. "While the cost of deposits is repricing sharply across the system, there will be relatively lower yield expansion going ahead as most of the back-book has been repriced and there is a high competitive pressure on yields.
SBI Q3FY24 result review: A higher-than-factored weakness in the October-to-December quarter (Q3) results of State Bank of India (SBI), for financial year 2023-24 (FY24), has prompted brokerages to cut earnings estimates for the ongoing financial year. They, however, have maintained 'Buy' ratings on the stock, revising target price upwards in some cases, owing to the stock's recent underperformance relative to its peers.
After the latest rout, the American depositary receipt (ADR) premium of HDFC Bank to its local shares has shrunk to nearly zero. Shares of HDFC Bank on Thursday fell 3.1 per cent to Rs 1,490, extending its two-day decline to 11 per cent. Meanwhile, the ADR has slumped over 15 per cent in the past two trading sessions.

For over a decade, HDFC Bank consistently outperformed industry growth rates in both deposits and advances, maintaining impeccable asset quality. Amid a landscape where other banks struggled with soaring non-performing assets (NPAs), HDFC Bank thrived, eventually surpassing ICICI Bank to become the largest private sector lender in India. Its net interest margin (NIM) remained stable in the range of 4.1-4.4 per cent.

A Rs 525-crore contingency provision during the July-September period led to a 19 per cent fall in IndusInd Bank's share price on Friday (October 25). Contingency provisions are generally made when a lender expects more bad loans in the coming quarters. Shares of the bank on Tuesday (October 29) declined 1.53 per cent to settle at Rs 1,038.2 apiece on the BSE.

'I don't think we have ever seen such alignment of everything that we need in the banking sector.'

Ten more bodies were recovered from the site of an avalanche in Uttarkashi, taking the death toll to 26, the Nehru Institute of Mountaineering said on Friday.
India's bank credit remains resilient and is showing no signs of systematic risk, Reserve Bank of India (RBI) Deputy Governor Michael Patra said on Monday. A copy of the speech was uploaded on the RBI website on Thursday. "Bank credit is monitored as a lead indicator of overheating. Our assessment, based on a menu of approaches, indicates that current rates of credit expansion are not pointing to systemic stress building up. Illustratively, the credit gap - the difference between the credit to GDP ratio and its trend - is currently negative," said Patra, while delivering a speech in Cambodia.
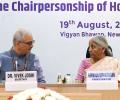
Finance Minister Nirmala Sitharman on Monday held a performance review meeting with heads of public sector banks and asked them to make concerted efforts to garner deposits. Deposits have been growing 300-400 basis points lower than the credit growth in the last few months, creating an asset-liability mismatch for banks. During deliberations on the deposit mobilisation, she said that while the credit growth has picked up, mobilisation of deposits could further be improved to fund the credit growth sustainably, and asked banks to make concerted efforts to garner deposits by conducting special drives.
Banks enjoyed an expansion in Net Interest Margins (or NIMs) as well as in credit demand through the 2022-23 financial year (FY23). The credit expansion was because economic growth continued to recover from the Covid-19 years, and indeed, second half GDP growth surprised on the upside. The NIM expansion was because banks raised lending rates immediately (in many cases automatically due to floaters) as the Reserve Bank of India (RBI) hiked policy rates, and only started raising deposit rates late into the fiscal.

'For the first time ever it has come below 1 per cent, at 0.97 per cent.'
Public sector banks (PSBs) have delivered significant outperformance over the past three years and the sector has been re-rated. Given the growth and profitability expectations of an 18 per cent return on equity (RoE) over FY24-26, there is still a case for buying at the current levels. While the net interest margins or NIMs may remain range-bound or have a downward bias, there's optimism about possibly better opex ratios and lower non-performing assets (NPAs), plus scope for further credit cost reduction, and healthy treasury performances as interest rates trend down.
ICICI Bank reported good results for the October-December 2023 quarter (Q3), with 24 per cent year-on-year (Y-o-Y) growth in profit after tax (PAT). Net interest margin (NIM) dropped 10 bps quarter-on-quarter (Q-o-Q) to 4.43 per cent. Credit growth was at 19 per cent Y-o-Y (4 per cent Q-o-Q), while deposit growth was at 19 per cent Y-o-Y (3 per cent Q-o-Q).
Public sector banks (PSBs) posted 16.1 per cent year-on-year (Y-o-Y) growth in net profit at Rs 39,974 crore during the June 2024 quarter. While net interest income (NII) showed subdued growth of 7.1 per cent, provisions and contingencies declined by 10.5 per cent Y-o-Y. This aided the bottom line to show steady growth.

Mumbai City FC grabbed their maiden victory of the Indian Super League (ISL) 2024-25 season with a closely-fought 2-1 win against FC Goa in Margao on Saturday.
An in-line ICICI Bank result for the quarter ended March 31, 2024, has led to analysts raising target price and earnings per share (EPS) forecast on the stock. ICICI Bank, they said, appeared least vulnerable to regulatory action on its digital offerings or for risk monitoring lapses.
Fundraising through qualified institutional placement (QIP) has revived this year, led by commercial banks, after a lacklustre 2022. According to data compiled by Prime Database, Indian companies have raised Rs 53,070 crore in 2023 so far, of which seven banks - Union Bank of India, Indian Bank, Bank of India, Federal Bank, IDFC First Bank, Bank of Maharashtra, and J&K Bank - account for Rs 21,290 crore, or about 40 per cent. If other financial institutions are included, the figure surges to Rs 26,690 crore.

Twenty-seven mountaineers remained missing on Wednesday after rescue workers brought 14 injured members of their team to safety, a day after an avalanche claimed 10 lives in Uttarkashi.

'If individual stocks start falling 25% to 30% or more, then I doubt how many of them will be able to withstand that (kind of selloff). That is when you'll see panic coming in.'
HDFC Bank's market capitalisation (market cap) touched Rs 13 trillion in Thursday's (December 28, 2023) intra-day trades as the largest private sector lender is set to report its sharpest monthly rally in the past two years. At 10:33 AM; HDFC Bank's market cap stood at Rs 13.03 trillion, the BSE data shows. The stock was up 1 per cent at Rs 1,717.90 in intra-day trades on December 29, inching towards its record high of Rs 1,757.80 touched on July 3, 2023.

Bank of Baroda Q4 results: Key brokerages have raised their target prices on Bank of Baroda after the state-owned lender posted better-than-expected March quarter (Q4FY23) results. Analysts now see up to 29 per cent upside in the stock from a one-year perspective as they believe BoB is well-placed among the large public banks with nearly all key business metrics moving closer to the top-tier banks. Valuations, too, remain attractive despite steady strong quarterly performances.
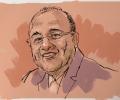
Sashidhar Jagdishan, managing director and chief executive officer of HDFC Bank, the largest private-sector lender of the country, has just completed his first term. The period October 2020-October 2023 was a roller coaster, and the second one, which started on October 27, could be more interesting as the lender absorbs the impact of the merger of HDFC, which was integrated on July 1, and moves to the next growth phase. Soon after he took over the reins from Aditya Puri on October 27, 2020, the Reserve Bank of India (RBI) debarred HDFC Bank from enrolling new credit card customers and launching new products under the Digital 2.0 programme due to repeated outages on its mobile-banking and internet-banking platforms.
Benefitting from the economic rebound, banks are expected to report a healthy bottom-line and asset quality profile in the quarter ended March 2023 (Q4FY23). The net profit of listed commercial banks is projected to grow by an average 43.6 per cent year-on-year (YoY) in Q4FY23 amid better net interest margins (NIMs) and declining credit costs. This is based on a combined assessment of analyst estimates for 17 banks on Bloomberg database.

Images from Indian Super League matches played on Saturday.
Banks, the biggest component of the Indian equity market, are now trading at a big discount to the benchmark indicesThe BSE Bankex index, which tracks the share price of the 10 top listed banks, is trading at a trailing price to earnings (P/E) multiple of 15.3X, nearly a 40 per cent discount to the BSE Sensex current P/E of 24.37X. This is the biggest valuation gap between the two indices in at least 10 years. Similarly, the BSE Bankex price to book ratio (P/B) of 2.22X is 40 per cent lower than the current Sensex P/B ratio of 3.61X.

India's largest PSU bank, State Bank of India, delivered excellent results, once the impact of a big jump in employee expenses was adjusted for. The net interest income (NII) beat the Street due to a better net interest margin (NIM) and good loan growth. The credit growth at 5.2 per cent quarter-on-quarter (Q-o-Q) (15 per cent year on year) was excellent for a large bank.
It is 10 years since Bandhan Financial Services became the first microfinance institution (MFI) to receive the universal bank licence. A year later, in 2015, it started operations. Bandhan's entry into banking was seen as a vote of confidence by the Reserve Bank of India (RBI) for the country's microfinance sector. Subsequently, the RBI awarded small finance bank licences to nine MFIs.

We'll need to wait a couple of years to see how many restructured loans turn bad and whether some banks fall victim to their obsession for growth, explains Tamal Bandyopadhyay.
