
Importers are rushing to hedge their dollar positions amid the sharp depreciation of the rupee against the American currency and expectations of further volatility even as exporters are holding off after suffering mark-to-market (MTM) losses on earlier hedges.

The stock of State Bank of India (SBI) may re-rate soon, believe analysts, if the lender manages to safeguard its net interest margin (NIM) going ahead. This, along with controlled credit costs, should aid the outlook of the stock which has been underperforming the markets for some time now. "We believe delivery of growth on guided lines, sustenance of NIMs near current levels, and controlled asset quality parameters aiding controlled credit costs should lead to strong profitability and drive re-rating of the stock," said analysts at JM Financial.

Re-rating of Axis Bank's stock may continue in the near-future, believe analysts, as the risk-reward on the stock remains favourable amid healthy financials. The bullish stance comes after the Mumbai-based lender delivered a strong outperformance in the March quarter of fiscal year 2023-24 (Q4FY24) on core pre-provision profit and net profit, with improving asset quality. Axis Bank's net interest margin (NIM) expanded, against expectations, even in a tough market.

'The government's decision to keep interest rates unchanged on small savings schemes will certainly constrain banks' ability to cut deposit rates further.'
The Reserve Bank of India (RBI) on Friday delivered a 25 basis point (bps) repo rate cut analysts expected, driven by the strong 8.2 per cent GDP growth in the September quarter. However, analysts do not expect a runaway market rally as the impact of US tariffs continues.
ICICI Bank delivered satisfactory results in the second quarter of 2025-26 (Q2FY26), sustaining return on assets (RoA) of around 2.3-2.4 per cent and improving asset quality. Provisions declined 26 per cent year-on-year (Y-o-Y) and 50 per cent quarter-on-quarter (Q-o-Q).

Bajaj Finserv - the holding company of Bajaj group's financial services business - has laid out plans for the next five years. During this period, it is eyeing 18-22 per cent compound annual growth rate (CAGR) in net profit at Rs 21,000-24,000 crore on a consolidated basis.

With the price of gold entering a strong bull run, gold-loan non-banking financial companies (NBFCs) are under the spotlight, even though their performance is not directly linked to gold price. Muthoot Finance outperformed in the April-June quarter (Q1) of 2025-26 (FY26), with its assets under management (AUM) growing 10 per cent quarter-on-quarter (Q-o-Q) and 42 per cent year-on-year (Y-o-Y), an improvement of 88 basis points (bps) Q-o-Q in net interest margin (NIM), and a fall in credit cost. Gold AUM rose 40 per cent Y-o-Y and 10 per cent Q-o-Q. The company recorded recoveries of 350 crore, including 100 crore from an asset reconstruction company (ARC), resulting in a 100-bp Q-o-Q yield increase.

As deposit growth lags credit expansion, Indian banks face shrinking low-cost Casa inflows, rising funding costs, and structural shifts driven by UPI, e-Kuber, and digital savings trends, points out Tamal Bandyopadhyay.
Axis Bank reported a sharp drop in net profit in the second quarter of financial year 2026 (Q2FY26) on higher provisions and weak operating profit growth while revenue growth was moderate. But loan growth and deposit growth improved to double-digits year-on-year (Y-o-Y) and asset quality also improved with the gross non-performing loan or NPL ratio moving down.

Finance Minister Nirmala Sitharaman on Tuesday allayed apprehension that privatisation of state-owned banks would hurt financial inclusion and national interest. She said the bank nationalisation done in 1969 has not yielded the desired result as far as financial inclusion was concerned.

Public-sector banks (PSBs) are attracting the attention of investors and the PSU Bank Index has gained nearly 10 per cent in the past month. PSBs have seen return on assets (RoA) climbing to 1 per cent in 2024-2025 (FY25) and margins are believed to have moved up further in the first half of this financial year (H1FY26) with asset quality remaining stable.

'MIB which is a part of retail, will grow in the range of 20 per cent.'

'This is an area where good lending can happen, and that is one of the priorities for the next quarter.'
Net NPAs increased to Rs 36,260 crore in the December quarter from Rs 34,843 crore in September and Rs 33,116 crore in December 2023, observes Tamal Bandyopadhyay.
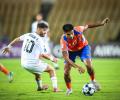
The match simmered, waiting for a spark, until Al Zawraa found it on the cusp of half-time. Hassan Abdulkareem's clever ball found Kadhim Raad, who cut back for Reziq Banihani. A messy deflection, a ricochet off Nim Dorjee Tamang, and the ball nestled cruelly into Goa's net.
In Q1FY26, the bank reported fresh slippages of 8,200 crore, up 71 per cent Y-o-Y and sequentially. Of this, 7,500 crore is from the retail segment.

Shriram Finance's (SHFL's) profit after tax (PAT) rose 10 per cent year-on-year (Y-o-Y) to Rs 2,140 crore in the fourth quarter of the financial year 2024-25 (Q4FY25).
Banks have outperformed the broader market in the past six months and most of the leading lenders have given positive returns to investors compared to a negative return delivered by benchmark indices.
The Reserve Bank on Thursday affirmed its commitment to continue with its supervisory measures aimed at early identification of risks and vulnerabilities. The central bank would also focus on enhancing cyber resilience and capabilities of Supervised Entities (SEs) by implementing the recommendations of the inter-regulatory Working Group, which has uniform baseline cybersecurity guidelines for financial entities, it said in its annual report.

'Now we have one of the best asset qualities in the industry.'

Despite sharp interest rate cuts expected in this financial year amid easy liquidity conditions, state-run banks are treading cautiously on their loan growth projections for FY26. Most large banks are projecting loan growth at 11-13 per cent, almost similar to the previous financial year.
Privately, many bankers admit their immediate goal is not growth but slowing the erosion of Casa deposits, reveals Tamal Bandyopadhyay.
Kotak Mahindra Bank's net interest margin is likely to swell after the Reserve Bank of India (RBI) lifted its restrictions on the private lender that barred it from issuing fresh credit cards and onboarding new customers through digital mode, brokerages said on Thursday. The bank's net interest margin (NIM) has seen a decline of over 35 basis points (bps) since the restrictions were imposed by the regulator in April 2024.
Moody's Ratings on Wednesday said India's economic growth will exceed 6.5 per cent in the next fiscal, up from 6.3 per cent this year, on higher government capex and consumption boost from tax cuts and interest rate reduction. Projecting a stable outlook for the banking sector, Moody's said although the operating environment of Indian banks will remain favourable in the next fiscal, their asset quality will deteriorate moderately after substantial improvements in recent years, with some stress in unsecured retail loans, microfinance loans and small business loans.
The April-June quarter (Q1) of the current financial year (FY25) may be soft for banks with loan growth moderation, net interest margin (NIM) pressures, and higher staff and credit costs inching up, according to analysts. Credit growth could ease due to the lagged impact of the Reserve Bank of India (RBI) tightening and deposit growth has weakened, and the current account and savings account (CASA) ratio has declined 10-370 basis points (bps) quarter-on-quarter (Q-o-Q) for many banks.
In 2025 banks are in for challenges such as pressure on margins and slowing credit growth. With the likelihood of a repo rate cut in February or April, external benchmark-linked loans of banks will be repriced immediately. However, deposit rates are expected to adjust more gradually, which could impact the net interest margin (NIM) - a key measure of profitability for banks.
Union Finance Minister Nirmala Sitharaman's call for making lending rates affordable may not resonate anytime soon as banks still struggle with margin compression, and await clues from the Reserve Bank of India (RBI) on liquidity and rate action. Hinting that any lending rate cut was some time away, State Bank of India (SBI) managing director Vinay M Tonse said there was still some aggression in the market regarding deposit pricing.

LIC Housing Finance (LICHF) delivered a healthy FY24 with improvements in net interest margin (NIM) and credit costs and an improved return on assets of 1.7 per cent compared to an average of 1.3 per cent between FY14-FY23. Loan growth was low due to technology upgrades to the platform in H1FY24, though momentum improved in H2FY24. In Q4FY24, the net interest income (NII) came in at Rs 2,250 crore.
Brokerages expect a further slowdown in Indian firms' revenue and earnings growth in Q4FY25, following low single-digit growth in the preceding three quarters, as factors like weak consumer demand and credit growth linger on.
The cost of deposits is on the rise, but banks can't raise interest rate on close to 60% of their loan books, points out Tamal Bandyopadhyay.
Engineering and construction major Larsen & Toubro (L&T) reported a 25 per cent rise in net profit attributable to the owners of the company for the January-March quarter of 2024-25, owing to higher revenues and an exceptional gain. For the quarter under review, L&T posted a consolidated net profit of Rs 5,497.3 crore, while revenue rose 10.9 per cent year-on-year (Y-o-Y) to Rs 74,392.28 crore.
'We may see little softness in liquidity position after the stabilisation of the government.'
Banks are likely to see their net interest margins (NIM) - broadly the difference between interest earned on loans and paid on deposits - shrink by another 30 basis points (bps) over the next few quarters. After hitting a peak of 3.3 per cent in the third quarter (Q3) of the financial year ended March 31, 2023 (FY23), NIMs have been on a downward trajectory, touching 3.13 per cent in Q2FY24 on higher cost of funds, according to capital markets firm CARE Ratings. Banks are still grappling with the Reserve Bank of India's policy rate increases - that have made deposits costlier as the interest payable to customers has increased - and the regulatory actions on unsecured lending.
Growing concerns over slower-than-expected margin recovery, amid weak deposit growth have caught HDFC Bank's investors off guard. HDFC Bank's stock on Wednesday plunged nearly 9 per cent to hit an intraday low of Rs 1,527 on the BSE after reporting weaker-than-expected earnings in the third quarter (October - December) of the current financial year (Q3FY24). The shares of India's biggest private lender closed at Rs 1,536.9, down 8.46 per cent.
Weakness in HDFC Bank's net interest margin (NIM) might have bottomed out in the July-September quarter (Q2-FY24), analysts said on Tuesday, as most of the merger-related one-time adjustments have been done. The bank, they believe, should be able to grow from here on, allowing the stock to reverse its underperformance. "The weak NIM print was not unexpected given the merger and regulatory impact caused by the incremental cash reserve ratio (ICRR; 5-10 bps for the quarter).
As the fight for deposits intensifies, the cost of money will rise and the margin will be under further pressure, points out Tamal Bandyopadhyay.

State-owned Indian Renewable Energy Development Agency's (Ireda's) chairman and managing director Pradip Kumar Das has announced that the company has requested the government to allow it to carry out a follow-on public offer (FPO) as it will need further equity infusion to maintain the pace of growth. The FPO would aim to raise between Rs 4,000 crore and Rs 5,000 crore. Ireda, which provides funding assistance and other services to renewable energy and energy efficiency/conservation projects and is 75 per cent owned by the government of India, has requested the Union Finance Ministry to be included under Section 54EC of the Income Tax Act, which will help reduce borrowing costs.
With high credit growth and healthy asset quality, listed commercial banks are expected to report steady growth in earnings during the fourth quarter ended March 2024 (Q4 FY24). Profits are expected to grow at 9.6 per cent year-on-year (Y-o-Y) and net interest income (NII) by 8.7 per cent in Q4 FY24, according to Bloomberg analysts' estimates. According to Motilal Oswal Securities, while bank credit growth has been robust, deposit growth has also gathered pace.
Corporate India's struggle with subdued revenue and earnings growth persisted in the October-December quarter of 2024-25 (Q3FY25). The combined net sales (gross interest earnings for lenders) of listed companies grew in single digits for the seventh consecutive quarter, while their combined net profit rose by a single digit for the third straight quarter.
