Razorpay CEO Harshil Mathur highlights India's leadership in real-time payments, stating it can foster numerous billion-dollar fintech companies capable of expanding globally. He draws parallels with the US internet boom and discusses how India's unique regulatory and private sector collaboration, exemplified by UPI, can be replicated in other emerging markets. Mathur also touches upon the opportunities and risks associated with leveraging AI in business.
India is emerging as Claude.ai's second-largest user base, driven by strong adoption in coding, maths and enterprise AI tasks.

Fintech unicorn Razorpay has raised $375 million in the Series F round of funding at a $7.5-billion valuation, making it India's second-most valuable start-up in this space, after Paytm. The company valuation has surged over seven times in 15 months, helping it push Walmart-owned digital payments firm PhonePe to the third spot on the country's most-valuable fintech list. Razorpay's latest round of fundraising was led by Lone Pine Capital, Alkeon Capital, and TCV.

RMG firms Dream11, Games24x7, Gameskraft and MPL lost unicorn status after the gaming ban while fintech players led 11 new unicorns added in 2025.

'Our focus would be to onboard top 100 merchants in top 10 different segments.'

'This marks a turning point for Paytm, with the regulatory environment looking much clearer than it has been in the last two years.'

As quick commerce gains ground, emerging direct-to-consumer (D2C) brands are betting big on digital channels to drive growth. According to Aman Gupta, co-founder of wearables brand BoAt, new-age brands in India have been expanding at a much faster pace than expected, driven by digital channels like quick-commerce. "Investors doubted the potential of D2C brands when we started, but today there are multiple brands in the startup market that are growing on the shoulders of these digital channels," Gupta said while addressing a session at Razorpay's D2C and Retail Summit recently.

'For smaller merchants, there should be a process that is digital and a minimum KYC journey should be allowed.'
Unacademy may see a funding dry spell for at least next 12-18 months and even last till 24 months and will cut costs to weather the lean period, said the chief executive of the education technology unicorn that recently laid off more than 600 employees. "This is a test for all of us. We must learn to work under constraints and focus on profitability at all costs. We must survive the winter," said Unacademy's co-founder and CEO Gaurav Munjal in a letter to the employees. "Winter is here. We are looking at a time when the funding will dry up for at least 12-18 months.

WhatsApp's advantage is that it is the first app millions of Indian check first thing in the morning and innumerable times during the day and night.

WhatsApp on Wednesday announced the expansion of its payments service in India to make it easier for people transacting with businesses to pay for purchases directly in the chat, with a choice of UPI apps, including rival digital payment options, as well as credit and debit cards. Meta founder and CEO Mark Zuckerberg asserted that India is leading the world in people and businesses embracing messaging. WhatsApp said it is working with partners Razorpay and PayU "to make paying for something as simple as sending a message", as the Meta-owned platform unveiled a host of new features to woo businesses in India's booming commerce market.

More than three weeks have passed since the Reserve Bank of India's (RBI's) new guidelines on e-mandates for recurring payments came into effect but consumers are still taking to social media platforms to complain about the disruptions they are facing. This comes as most stakeholders in the ecosystem have not put in place systems in accordance with the new rules, resulting in many transactions not going through. Industry sources said most banks are still not ready, especially the smaller ones.
This makes it the most valued fintech company in the country after Paytm and Walmart-owned PhonePe.
If you have seen Zwigato, Param Kumar's story will sound familiar. Laid off from his job as a repairman at a Gurugram-based water purifier provider, he now delivers groceries and food for a mobile-based delivery app, in Delhi. Kumar, who started making deliveries last August, told Business Standard that he is working longer hours than his older salaried job as an RO repairman, and has no paid leaves or health insurance. Kumar is part of India's estimated 7.7 million-strong force of gig workers.
In January, Visa's chief executive officer, Al Kelly, said during an earnings call that "there's been a burst of the balloon in valuations in the fintech world". Noting that the trend of lower valuations "is a helpful characteristic of the current environment", he added: "We will look for capabilities and management teams that will bring more value to Visa than we can bring ourselves." Data from KPMG's Pulse of Fintech H2'22 shows that global fintech investment - via mergers and acquisitions (M&As), private equity (PE) and venture capital (VC) firms - at $164.1 billion in 2022, was down 31 per cent over the year before. Indian fintechs held up better during this timeframe, attracting $6 billion, or a fall of 24 per cent.

The coronavirus pandemic has changed how businesses look at payments. Earlier, fintech companies said when they were talking to merchants, they were not interested in digitisation.
Fresher hiring is expected to more than double compared to last year.

Experts say the new guideline is likely to hurt foreign players more, especially card companies such as Visa, MasterCard and American Express who process and store credit card transaction data outside of India.
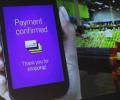
Apart from SBI, UPI 2.0 partner banks are HDFC Bank, Axis Bank, ICICI Bank, IDBI Bank, RBL Bank, YES Bank, Kotak Mahindra Bank, IndusInd Bank, Federal Bank and HSBC.
Fintech players are customising solutions for rural markets and helping SMEs learn how to use the services
While players in the financial ecosystem are opening up to the idea of receivables funding for the sector, this market needs a regulator, which a Parliament panel feels only RBI can provide.
Naveen Tewari loves cycling but over the past few years, he has been keeping his first love waiting.

'India missed the software products revolution (and now is in danger of missing the platform revolution), complacent that we are the software experts of the world based on IT services prowess,' points out Rajeev Srinivasan.
