For Paris-headquartered IT services major Capgemini, India has always been the backbone of its services delivery for its global clients, but the company is focused on driving more value from India as it gears up its engineering research and development (R&D) presence worldwide with its acquisition of Altran Technologies. The company, which has about 149,000 employees in India, is looking to hire 60,000 associates this year. Of them, 30,000 will be recruits from campuses and the rest lateral entrants. For Ashwin Yardi, chief executive officer India, Capgemini, the focus is to make sure that the India unit is aligned with the global plans of repositioning the company as a hub of engineering R&D, operational technology, and IT.
The current up move, according to analysts, closely resembles the rally post the global financial crisis in 2008-09, not just in quantum and speed, but also the way small-and mid-cap indices outperformed large-cap peers.

sharper-than-expected economic recovery back home, analysts say, can fuel a further rally in domestic cyclicals, industrials, and financials as global central banks continue with their easy money policy.
In terms of stock selection, India continues to benefit from two phenomena - the big getting bigger and availability of quality stocks in relative abundance compared with its Asian peers.
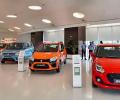
Passenger vehicle market leaders Maruti Suzuki and Hyundai on Saturday reported a decline in wholesales in December 2021, although homegrown majors Tata Motors and Mahindra & Mahindra reported growth, amid semiconductor shortage continuing to impact production. Other manufacturers Nissan and Skoda also reported an increase in December 2021 sales although Honda Cars India witnessed a decline last month. The country's largest carmaker Maruti Suzuki India (MSI) reported a 4 per cent fall in wholesales to 153,149 units in December 2021 as against 160,226 units a year ago.

'Today, there is no easy money to be made after the run-up in equities.'

'It is less dependent on imported capital.'

Markets
Without exception, the top four majors beat Street estimates across all parameters - revenues, profitability, or net profit growth. However, what stood out were the large deal wins reported by the big two, TCS and Infosys.
While analysts remains overweight on financials, property, discretionary, industrials and materials, they maintain a neutral stance on pharma, telecom and energy; and underweight on staples, utilities, and IT services.
Analysts attribute the surge to a host of factors, particularly the interest shown by the retail investors in these two market segments.
The key demand drivers -- such as low home loan rates and income tax sops, particularly for affordable housing -- that supported the recovery in H2 FY2021, remain in place and will spur recovery again, feel experts.

Investment in market leaders with a safety-first approach could yield reasonable returns across sectors.
