The Reserve Bank of India (RBI) is planning to extend tokenisation to various financial asset classes, building on its successful trials with certificates of deposit (CDs). This move aims to enhance the efficiency of issuance, trading, and settlement of financial assets, leveraging blockchain technology and wholesale Central Bank Digital Currency (CBDC) for atomic settlements.

Infosys Chairman Nandan Nilekani stressed the need for India to develop population-scale tokenisation infrastructure capable of handling billions of transactions, rather than merely focusing on issuing tokens. He highlighted the importance of interoperability, liquidity, and high volumes for tokenisation to expand across various asset classes and use cases.

India's markets regulator Sebi has launched 'Demat 2.0', a pilot project for tokenisation of corporate bonds, enabling atomic settlement through integration with RBI's wholesale CBDC. This new market infrastructure uses Distributed Ledger Technology (DLT) to make bond issuance, trading, and settlement faster and more efficient. India is the first country to issue corporate bonds natively on a distributed ledger with central bank digital currency settlement. Additionally, RBI Governor announced new UPI innovations: 'Tap & Pay' for faster POS transactions and MyUPI, an AI-powered customer support solution.

RBI Governor Sanjay Malhotra reiterated India's cautious stance on cryptocurrencies due to concerns over monetary sovereignty and capital flows, while actively promoting underlying technologies like distributed ledger technology and tokenisation. He also addressed the global rise in public debt and hardening bond yields, attributing it to increased government and private spending, including that driven by AI, and noted the implications of global interest rates on India's monetary policy.

Finance Minister Nirmala Sitharaman has urged the Reserve Bank of India to accelerate its central bank digital currency initiatives, emphasising the need to sharpen capabilities with the digital rupee amidst rapid advancements in tokenisation, agentic AI, and quantum computing. She also highlighted critical concerns regarding cybersecurity, warning that autonomous AI systems are evolving rapidly and require robust safeguards. Sitharaman proposed a federated industry platform to give India's technology ecosystem a collective international voice.
Chandigarh is set to launch the Central Bank Digital Currency (CBDC), or digital rupee, for Direct Benefit Transfer (DBT) under the Pradhan Mantri Garib Kalyan Anna Yojana (PMGKAY) on August 14. This initiative makes Chandigarh the first Union Territory to fully roll out CBDC-based DBT for food subsidy, enhancing transparency and efficiency in welfare delivery. The digital rupee, issued by the RBI, will be purpose-bound for purchasing foodgrains from authorised merchants.

Authorised push payment frauds have emerged as a growing challenge globally as scammers increasingly rely on social engineering techniques to persuade users to transfer money voluntarily, making recovery more difficult even when transactions are authenticated.
The Reserve Bank of India (RBI) has introduced its 'Payments Vision 2028' document, outlining initiatives to enhance digital payment security, introduce electronic cheques, and expand regulatory oversight to include e-commerce entities.

Come October 1, merchants, payment aggregators and acquiring banks can no longer store the card details of customers.
From April 1, 2026, the Reserve Bank of India's new authentication directions modernise how every digital payment you make must be verified -- and place the burden of security squarely on your bank, not on you.
Tokenisation is the process of replacing debit and credit card numbers with a set of characters or tokens.
The Reserve Bank of India's (RBI) new rules for credit and debit cards came into effect from October 1. These include tokenisation, one-time password (OTP) for activation after 30 days, written permission for enhancement of credit limit, and greater clarity on interest calculation.
The Reserve Bank of India (RBI) on Friday extended the card-on-file (CoF) tokenisation deadline by three months to September 30, 2022, in view of various representations received from industry bodies. Card-on-file, or CoF, refers to card information stored by payment gateway and merchants to process future transactions. Tokenisation is the process of replacing actual card details with a unique alternate code called 'Token' - thereby enabling more secure transactions.
The Reserve Bank of India (RBI) recently said no entity in the card transaction or payment chain, apart from the card issuers and card networks, will be allowed to store sensitive user data from January 1, 2022. Instead, in transactions card data will be converted to tokens.
The Reserve Bank of India (RBI) on Thursday extended the card-on-file (CoF) tokenisation deadline by six months to June 30, 2022, in view of various representations received from industry bodies. Card-on-file, or CoF, refers to card information stored by payment gateway and merchants to process future transactions. The earlier deadline was December 31, 2021. "In light of various representations received in this regard, we advise...the timeline for storing of CoF data is extended by six months, ie., till June 30, 2022 and post this, such data shall be purged," RBI said in a notification addressed to all payment system providers and payment system participants.
'We have seen that stablecoins lack the basic attributes of money, their advantages are neither unique nor unambiguous and their risks are all too real.'

If implemented in India, the service will allow passengers book security screening slots in advance, helping cut down wait times in long queues.

Tokenisation acts as an additional layer of security as it masks sensitive card data such as the 16-digit account number, expiry date and security code. However, the security level of the app and the customer's mobile itself also needs to be taken into consideration, say experts. Nikhat Hetavkar explains the whole idea of tokenisation, how it is enabled, its impact on card transactions and related security guidelines.
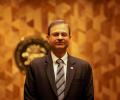
Reserve Bank Governor Sanjay Malhotra on Wednesday exhorted the fledgling fintech ecosystem to focus on the underserved sections of the society to deepen financial inclusion. Speaking at the annual Global Fintech Fest in Mumbai, Malhotra accepted that serving the "privileged" will be a lucrative business, but urged the smaller companies to focus on the underserved.

There is a need for real-time or near real-time credit reporting, instead of the current fortnightly system, to improve underwriting precision, enable timely reflection of borrower actions such as loan closures or repayments, and deliver a superior consumer experience, Deputy Governor of the Reserve Bank of India (RBI), M Rajeshwar Rao said on Wednesday.
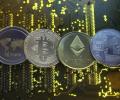
Widespread use of crypto assets, including stablecoins, can have a negative impact on the macroeconomic and financial stability of a country, the Reserve Bank of India (RBI) said on Monday. In its Financial Stability Report (FSR), the banking regulator highlighted that excessive use of crypto assets can reduce effectiveness of monetary policy, worsen fiscal risks, circumvent capital flow management measures, divert resources available for financing the real economy and threaten global financial stability.
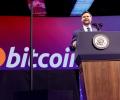
In a major initiative, Pakistan has announced the establishment of its first government-backed Strategic Bitcoin reserve as it invited investment in the country's crypto markets.
'Skills like critical thinking, empathy, storytelling, team management and ethical judgment will grow in value even as AI continues to master logical tasks,' says Alphabet and Google CEO Sundar Pichai.

'It allows everybody to participate and controls all assets.' 'We want to have something that allows everyone to participate and control all kinds of assets.'

The Reserve Bank of India (RBI) on Wednesday issued a draft framework for alternative authentication mechanism for digital payments, wherein it has mandated that all digital payment transactions would have to be authenticated with an additional factor of authentication (AFA), except small value contactless card payments for up to Rs 5,000 at point of sale terminals, e-mandates for recurring transactions, and small value digital payments through offline mode, among others. Additionally, it has said that all digital payment transactions, other than card present transactions, have to ensure that one of the factors of authentication is dynamically created, i.e., the factor is generated after initiation of payment; is specific to the transaction; and cannot be reused.
In a bid to ensure security of card data, the Reserve Bank of India (RBI) has enhanced the scope of tokenisation and permitted card issuers to act as token service providers (TSP). Under tokenisation services, a unique alternate code is generated to facilitate transactions through cards. The RBI on Tuesday extended the device-based tokenisation to card-on-file tokenisation (CoFT) services, a move that will bar the merchants from storing actual card data. Card-on-file refers to card information stored by payment gateway and merchants to process future transactions.

The recent Reserve Bank of India (RBI) norms on tokenisation services, which will be offered by card networks, are likely to result in merchants and payment aggregators incurring a cost as they have to pay a fee to the networks. The merchants and the payment aggregators, in turn, may pass on the cost to the customers. The norms, which were issued by the banking regulator released on September 7, allow card networks like Visa and Mastercard to offer the tokenisation service.
The Reserve Bank of India (RBI) has relaxed card-on-file data storage norms pertaining to guest transactions checkout, whereby now, apart from the card issuer and the card network, the merchant or its payment aggregator involved in the settlement of the transactions can save the data for a maximum of T+4 days or till the settlement date, whichever is earlier. And, acquiring banks have been permitted to store the card-on-file data until January 2023 for handing other post-transactions activities. The industry reached out to the RBI on the issue and sought a solution.

The Financial Intelligence Unit-India (FIU-India), the national agency responsible for analysing suspicious financial transactions, has received requests from four more offshore crypto exchanges to operate in India again, said a senior government official familiar with the matter. In the beginning of 2024, India had banned nine crypto exchanges - Binance, Kucoin, Huobi, Kraken, Gate.io, Bitstamp, MEXC Global, Bittrex, and Bitfenix - for non-compliance with anti-laundering law in the country.
Reserve Bank of India governor Shaktikanta Das on Monday said payments through UPI (unified payment interface) have grown exponentially in the past 12 months with daily transactions crossing 36 crore, which is up 50 per cent from 24 crore in February 2022. In value terms, these transactions are worth Rs 6.27 lakh crore, registering a growth of 17 per cent from Rs 5.36 lakh crore in February 2022, the governor told reporters while launching the Digital Payments Awareness Week at the RBI headquarters in Mumbai this afternoon. He also said the overall monthly digital payment transactions crossed over Rs 1,000-crore-mark each month during the past three months.

Technology giant Apple has informed its customers in India that it will no longer store their card information on file and will not be accepting payments made by debit cards and credit cards for purchases or subscriptions on the App store or other Apple services. The decision has been taken by the US-based company in view of the Reserve Bank of India's (RBI's) card data storage guidelines, which will kick in from July 1. The deadline for implementing these norms was extended twice.
The payments industry is at a crossroads with the banking regulator on two pressing issues, neither of which seems headed towards an amicable solution. Depending upon which side accommodates the other, customers in India will have to choose between convenience and ironclad safety. In the end, the Reserve Bank of India (RBI), which regulates both banks and all payments services providers, will prevail. But the question is: will it do so by bending a little or by sticking to its firm stand? The two issues - one concerning payment facilitators storing customers' card details and the other about auto-renewal of payments - appear similar but aren't.

Humans will work far more collaboratively with artificial intelligence for rapid and complex decision-making.

Apart from the Google team led by AI scientist Manish Gupta, the company will also partner with the research community across the country to focus on tackling challenges in fields like healthcare, agriculture, and education.
Google on Thursday said it will offer users of Google Pay enhanced privacy features, allowing them to take control of their own transaction data. Google Pay is rolling out an update to the app from next week that will provide users with more controls to decide how their Google Pay activity is used to personalise features within the app. All users will be asked to choose whether they would like to turn the control on or off as soon as they upgrade to the next version of the Google Pay app.

Though chief executive officers from Google, Yahoo and Facebook have declined to attend the summit, the Apple CEO Tim Cook will address the meeting during which he will announce his intent to fold the government's cyber security recommendations into its own cyber strategy.
RuPay is working on how to increase offers to customers. It is also focused on technology innovation in the card payment system.
'When users sign up for free apps and services, they are giving up data. They fail to realise the impact of their data in the public domain, which is something that corporations have been monetising on for some time now.'

The 16-digit randomly generated number by the Aadhaar system was supposed to be introduced by the UIDAI on March 1 and mandatorily deployed by companies using Aadhaar by June 1.
