Crude and gas supply concerns have eased amid reports that Israel and Hamas have struck a peace deal. The International Energy Agency estimates oil demand may drop slightly in calendar 24 but Opec probably has enough pricing power to maintain $80/ barrel Brent prices. Russia's share of India's crude imports remained strong at about 35 per cent in September 2023.
The margins of tyre manufacturers could come under pressure given the rise in rubber prices and the moderating demand for tyres. In the past three quarters, the revenue growth for listed tyre companies has moderated from low to mid-single-digit on account of factors such as lower demand in replacement segments, weak export markets and the decline in the average selling prices to car makers (OEMs). Demand trends could remain muted in the near term, given the weak passenger vehicle replacement demand, assuming a typical replacement cycle of 3-5 years, and demand moderation in the OEM segment.
The headline for corporate profit growth has been very encouraging in the July-September quarter (Q2) of 2023-24 (FY24), with the combined net profit of listed companies up by 38 per cent year-on-year. However, the earnings distribution has been very lopsided, with most of the growth coming from public-sector oil-marketing companies (OMCs), banks, non-bank lenders, automobile (auto) companies, and cement producers. By comparison, companies from information technology services, fast-moving consumer goods (FMCG), retail, and consumer durables were disappointed, experiencing a sharp slowdown in net sales growth and a relatively muted increase in reported net profit.
Maruti Suzuki, Hyundai and Tata Motors reported a decline in wholesales in September as the companies curtailed dispatches to dealers to reduce inventory build-up amid a decline in demand. Maruti Suzuki India reported a 4 per cent dip in total domestic passenger vehicle wholesales last month to 144,962 units compared to 150,812 units in the year-ago month. The auto major said sales of mini segment cars, comprising Alto and S-Presso, grew marginally to 10,363 units against 10,351 units in September 2023.
Investors are increasingly turning optimistic about shares of new-age companies. From broad-based 'sell' calls, analysts are giving thumbs up to Zomato, Paytm, and FSN e-Commerce Ventures-owned Nykaa as these companies have shifted focus to sustainable profits. The shares of Zomato hit a fresh 52-week high of Rs 126 apiece on the BSE on November 7, having rallied 15.4 per cent in one week.
Metropolis Healthcare (MHL) has decided to acquire a 100 per cent stake in Gurgaon-based Core Diagnostics for Rs 247 crore. This is about 2.2x FY24 (financial year 2023-24) enterprise value (EV)/sales and estimated 14x FY26 EV/Ebitda for the deal.
There is no near-term respite for the country's largest fast-moving consumer goods maker, Hindustan Unilever (HUL), which is facing multiple challenges on the growth front. With demand showing no signs of improvement, especially in the rural segment, the October-December quarter (Q3) of 2023-24 (FY24) is likely to be similar to the previous quarter, with volume growth in the low single digits. The stock, which is down 7 per cent over the past year compared to the 11 per cent jump for the S&P BSE Sensex, could underperform the benchmark in the near term as well.
HDFC Asset Management Company (HDFC AMC) reported a healthy profit after tax (PAT) of Rs 430 crore for the July-September quarter (Q2) of financial year 2023-24 (FY24). It rose 20.2 per cent year-on-year (Y-o-Y) and decreased 8.4 per cent quarter-on-quarter (Q-o-Q). This was driven by good equity returns, leading to a sequential improvement in revenue yields.
After lagging behind benchmarks and broader indices over the past five years, real estate investment trusts (Reits) have outperformed them since the start of 2024. The four listed Reits have posted an average return of 16 per cent year-to-date, compared to 9.9 per cent for the S&P BSE Sensex and 11 per cent for the National Stock Exchange Nifty.
Capital goods companies in their Q2FY24 results are expected to report another steady quarter of earnings growth as order inflows and execution remain healthy, according to analysts. An upward revision in order inflow targets and a margin improvement due to lower raw material costs are also anticipated. "We expect the execution of all capital goods companies and most EPC (engineering, procurement, and construction) companies to remain healthy Y-o-Y (year-on-year), led by strong order book accretion in the past 5-6 quarters," wrote analysts at Kotak Securities in a note, estimating revenue growth of 32 per cent for India's largest company in the capital goods space -- Larsen & Toubro.

Titan Company on November 21, became the second Tata group firm to join Rs 3 trillion market capitalisation (market cap) club after its shares hit a new high of Rs 3,400, up nearly 2 per cent on the BSE in Tuesday's intra-day trade. At 12:28 PM; with a market cap of Rs 301,847 crore (Rs 3.02 trillion) Titan stood at number 16th position in overall market cap ranking on the BSE listed companies, the exchange data shows. Titan overtook paint company Asian Paints, which has a market cap of Rs 300,579 crore, data shows.
Domestic rating agency Icra on Monday revised its FY24 GDP growth forecast to 6.5 per cent from 6.2 per cent earlier. However, the revised forecast is still much lower than the Reserve Bank of India's (RBI's) 7 per cent real Gross Domestic Product (GDP) growth estimate for the ongoing fiscal. Earlier this month, the RBI had revised upwards its GDP estimate to 7 per cent from 6.5 per cent, calling the revised number a "conservative" one.

The fast-moving consumer goods (FMCG) sector has underperformed the Nifty over the past year as its 20 per cent return is trumped by 29 per cent of the benchmark index. The FMCG index saw a 2.2 per cent drop in the last session, while the Nifty lost 1 per cent. FMCG is seen as a defensive segment. The demand for staples like personal care products, groceries and snacks tend to be stable. FMCG companies are consistent dividend-payers.

Logistics major Delhivery has had promising Q2FY25 results. The Q2FY25 consolidated revenue was Rs 2,190 crore (up 0.8 per cent quarter-on-quarter or Q-o-Q and 12.8 per cent year-on-year or Y-o-Y). Express parcel revenue was Rs 1,300 crore, (up 1.7 per cent Q-o-Q/7.3 per cent Y-o-Y) alongside better yield (+5 per cent Y-o-Y) in the segment.
IT services major HCL Technologies (HCLTech) on Monday reported a 10.51 per cent increase in consolidated net profit to Rs 4,235 crore in July-September quarter of FY25, as the company raised the lower band of its growth guidance on the back of better-than-expected performance. The Noida-headquartered firm had posted a net profit of Rs 3,832 crore in the year-ago period. HCLTech increased the lower band of its revenue growth guidance to 3.5-5 per cent year-on-year in constant currency, against a guidance of 3-5 per cent in the first quarter.

The chemicals sector's recovery could be delayed until FY25 if the current trends of weak demand and flat pricing continue. Following a subdued September quarter, the revenue and profit performance of listed chemicals companies are anticipated to fall short of initial expectations of an improvement. Despite some price stability, the demand trajectory remains uncertain.
Even as banks and finance companies are reporting record-high earnings, their weighting in the benchmark National Stock Exchange Nifty50 Index has seen a downward trajectory. Investors expect a stronger performance from other sectors in the new year. Currently, banking, financial services and insurance (BFSI) companies collectively hold a weighting of 34.5 per cent, down from 36.7 per cent at the end of December 2022 and a record high of 40.6 per cent at the end of December 2019. This represents the sector's lowest weighting in the index since December 2021 when it stood at 33.7 per cent.

The July-September quarter (Q2) results for 2024-25 (FY25) from the largest listed consumer electrical solutions companies, Havells India and Polycab India, followed similar trends, demonstrating robust revenue growth while falling short of profitability expectations. Both companies witnessed overall growth in the 16-30 per cent range, but margins declined by 130-290 basis points (bps) year-on-year (Y-o-Y). Although brokerages are bullish on long-term prospects and have raised revenue projections, earnings forecasts have been revised downward due to margin pressures.
The Colgate-Palmolive (India) stock gained 2.3 per cent in trade on Friday, and ended at Rs 2,079 per share. This was on the back of a robust operating performance in the July-September quarter of 2023-24 (Q2FY24) and expectations of gradual sales recovery going ahead. While the stock is up 44 per cent from its lows in January this year, further gains will depend on its ability to sustain higher growth rates.

The Nifty IT index rose by 5.14 per cent on Friday (January 12), marking its best performance in a day since July 2020, followed by another 1.9 per cent rally on Monday. With this, the index, which tracks the share prices of India's 10 biggest information technology (IT) services companies, has increased 7.1 per cent in the past two sessions. However, the substantial rally in the index occurred at a time when India's four largest IT companies reported their worst quarterly performance in over five years.

Kajaria Ceramics, the country's leading listed tile manufacturer, has seen its stock fall by 7 per cent over the past month amid concerns about rising input costs and sluggish domestic demand. Other listed stocks also experienced weakness in September, although there was some recovery in October. While strong exports are expected to help stabilise domestic market prices, the surge in gas prices over the past couple of months may have impacted margins in the second half of FY24.
Foreign Portfolio Investors (FPIs) continued their buying spree and poured close to Rs 4,800 crore in the Indian equity markets in the first week of January driven by confidence in the country's robust economic fundamentals. Additionally, they injected Rs 4,000 crore in the debt market during the period under review, data with the depositories showed. With expectations of a prolonged decline in US interest rates in 2024, there is an anticipation that FPIs will likely escalate their purchase, particularly in the initial months of the New Year leading up to the general elections, V K Vijayakumar, chief investment strategist at Geojit Financial Services, said.
However, the second quarter of FY24 is expected to be muted, and, with that, the hope of double-digit growth is now being pushed to FY25. However, analysts are expecting the momentum in the closure of record total contract values (TCVs) will continue, as has been the case over the last two quarters.

There are conflicting views on Delhivery. The logistics player's results for the July-September quarter (Q2FY24) are being interpreted as good by some analysts and disappointing by others. As India's largest listed logistics player, the company stands to benefit from the formalisation across the mostly unorganised logistics space. Delhivery provides solutions to 23,113 customers, including e-commerce marketplaces, direct-to-consumer e-tailers, and enterprises across verticals.
Analysts are expecting pharmaceutical companies to post sales growth of 10-11 per cent in the second quarter this financial year while the Ebitda (earnings before interest, tax, depreciation, and amortisation) margins are anticipated to improve by about 110 basis points. Ebitda improvement will be led by lower input costs because prices of active pharmaceutical ingredients (APIs) are 5-15 per cent lower year-on-year (Y-o-Y). Axis Capital said sales growth would be around 10 per cent, of which growth in the India market would be 11 per cent or so.
ICICI Bank reported good results for the October-December 2023 quarter (Q3), with 24 per cent year-on-year (Y-o-Y) growth in profit after tax (PAT). Net interest margin (NIM) dropped 10 bps quarter-on-quarter (Q-o-Q) to 4.43 per cent. Credit growth was at 19 per cent Y-o-Y (4 per cent Q-o-Q), while deposit growth was at 19 per cent Y-o-Y (3 per cent Q-o-Q).
Growing concerns over slower-than-expected margin recovery, amid weak deposit growth have caught HDFC Bank's investors off guard. HDFC Bank's stock on Wednesday plunged nearly 9 per cent to hit an intraday low of Rs 1,527 on the BSE after reporting weaker-than-expected earnings in the third quarter (October - December) of the current financial year (Q3FY24). The shares of India's biggest private lender closed at Rs 1,536.9, down 8.46 per cent.

Reliance Industries Ltd on Monday reported a 5 per cent fall in the net profit for the July-September quarter, as weak oil refining and petrochemical business hurt operational performance.
Weakness in HDFC Bank's net interest margin (NIM) might have bottomed out in the July-September quarter (Q2-FY24), analysts said on Tuesday, as most of the merger-related one-time adjustments have been done. The bank, they believe, should be able to grow from here on, allowing the stock to reverse its underperformance. "The weak NIM print was not unexpected given the merger and regulatory impact caused by the incremental cash reserve ratio (ICRR; 5-10 bps for the quarter).
Notwithstanding record revenues in certain media sectors like film exhibition in the July-September quarter (second quarter, or Q2), the operational performance of the broadcasting business remained subdued. Zee Entertainment Enterprises and Sun TV are expected to experience a year-on-year (Y-o-Y) decline in advertising (ad) revenues during this period. Conversely, box office (BO) collections are anticipated to exceed Rs 3,000 crore in the quarter, propelled by a series of successful movie releases.

Once declared a dud stock, Suzlon has generated stellar returns for investors thus far this calendar year. On a year-to-date (YTD) basis, Suzlon's share price has doubled investor wealth by soaring 109.35 per cent on the bourses. By comparison, the benchmark BSE Sensex has gained just 11.2 per cent.

After a technology upgrade, the Multi Commodity Exchange of India (MCX) appears poised for an improvement in volumes. The premier commodity and forex exchange reported a loss of Rs 19.1 crore in the July-September quarter (second quarter, or Q2) of 2023-24 (FY24). This was attributed to higher software charges payable under an extended service agreement with 63 moons technologies and a one-off cost towards core guaranteed funds (CGF).
Oravel Stays, the parent company behind the travel tech brand Oyo, is eyeing to clock Rs 100 crore in Q4FY24 profit after tax (PAT) and a 20 per cent revenue growth for FY24, according to informed sources. These numbers were part of an internal review meeting between founder Ritesh Agarwal and senior management earlier this week, where he spoke about the company's profitability trajectory and growth in business.
After disappointing guidances in the first quarter (Apr-Jun) of the 2023-24 financial year (Q1FY24) and valuation downgrades, the Indian IT sector could see some positive repricing as the bad news for IT maybe easing in Q2FY24. A key negative factor was weaker demand from the US financial sector and from North America in general. The latest GDP (gross domestic product) estimates and sector-specific news suggest that the demand situation may not be quite so bad with a gradual recovery in tech spending in Q2.

Grasim Industries has announced a rights issue of around Rs 4,000 crore with the promoters committed to fully subscribing to their entitlements and to covering any unsubscribed portion. This is to part-fund capital expenditure (capex) of Rs 10,000 crore in a new foray into the paints business. The company has already invested Rs 3,640 crore in the paints business (by Q1FY24). The management has outlined a capex of Rs 5,700 crore for FY24, which includes Rs 4,280 crore allocated for the paints business, of which Rs 1,050 crore has already been spent in Q1FY24.

The Reserve Bank India's (RBI's) decision to ban the onboarding of new accounts on the "bob World" mobile digital platform led to a selloff in the Bank of Baroda (BoB) stock. The stock of the public sector bank dropped by around 3 per cent. The central bank cited "material supervisory concerns"; news reports claimed mobile numbers were randomly linked to accounts to purportedly inflate registrations on bob World.

UPL, the country's largest agrochemical company, had a weak July-September quarter (Q2), reporting a sharp fall in revenues across geographies. Overall, the revenues were down 19 per cent on the back of lower agrochemical prices and inventory destocking. While the overall volumes were down 7 per cent, prices fell by 15 per cent. Volume decline in the European market was on the back of high channel inventory and product bans while in India the fall by 27 per cent was on account of muted demand for segments such as cotton and pulses.
The 2023-24 (FY24) July-September quarter (second quarter, or Q2) proved to be a mixed period for asset management companies (AMCs). While the two largest listed AMCs, HDFC and Nippon, reported robust growth in both revenue and profits, the other two, Aditya Birla Sun Life and UTI, experienced profit declines. HDFC AMC reported an 18 per cent year-on-year increase in Q2 revenue to Rs 765 crore, while Nippon's revenue rose 15 per cent to Rs 475 crore.

HDFC Bank has been conscious in not accepting high-cost deposits, which have resulted in slower growth in October-December, said Sashidhar Jagdishan, managing director and chief executive officer, during an interaction with Goldman Sachs recently. He said during times of tight liquidity, short terms hardened, as was the case in October-December. "Not only did we participate, but we also gave up which came up for maturity," he said.
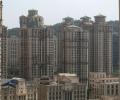
The S&P BSE Realty Index has emerged as one of the top-performing sectors, yielding a remarkable 45 per cent return over the past six months. The three leading players, listed by market capitalisation, have substantially enriched investor wealth by 43-70 per cent during this period. If the second quarter (Q2) of 2023-24 (FY24) updates from Macrotech Developers (Lodha) and Sobha, along with industry data for the quarter, serve as any indication, the trend of strong bookings for larger players is expected to continue.
