Bank employees entrusted with protecting customers' money are allegedly exploiting that very trust to steal from NRIs and elderly depositors through forged loans, liens and coordinated frauds.
Key Points
- A cross-bank syndicate is systematically defrauding NRIs and elderly citizens by creating fictitious loans against their fixed deposits using forged documents.
- The fraud operates in stages, involving bank staff creating liens, then using new loans from other depositors to cover tracks, often with proceeds invested in property.
- Detection of these organised, multi-institutional frauds is often accidental, recovery is incomplete, and accountability is diluted due to banks preferring quiet settlements.
- The current banking framework, including Core Banking Solutions and audit chains, has 'pockets of comfort' for insider fraudsters due to inadequate real-time oversight.
- Mandatory proactive notification systems for depositors, especially NRIs and senior citizens, with two-factor authentication for any term deposit transactions, are crucial to address vulnerabilities.
It had begun with a casual question.
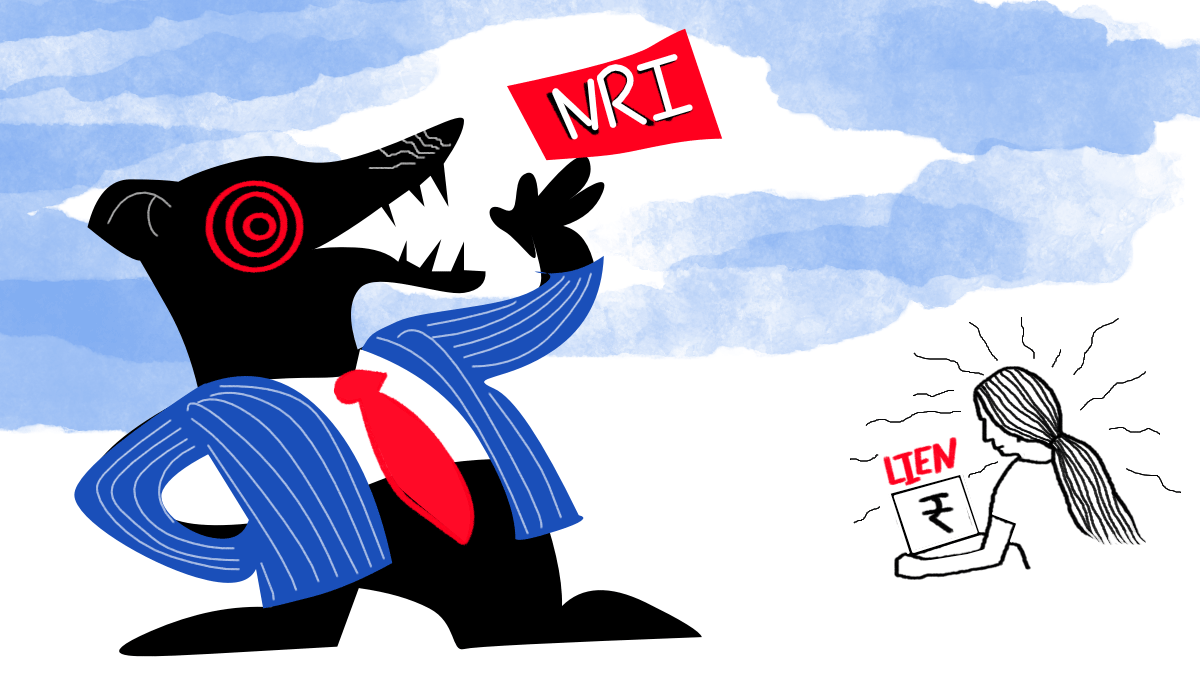
A non-resident Indian (NRI) customer, visiting her home branch after two years, noticed something unusual -- a lien mark on one of her term deposits, a deposit she had never pledged for any loan. She had never borrowed from this bank. Not once.
A lien is a legal right or claim that a bank or creditor holds on a customer's funds, assets, or property to secure the repayment of a debt or financial obligation.
When a lien is placed on a bank account, a specific portion of the account balance is temporarily blocked or frozen.
The customer can see the money in the total account balance but cannot withdraw, transfer, or spend that locked amount.
What followed was not just the unravelling of a fraud but the uncovering of a cross-bank syndicate -- a carefully orchestrated web of colluding employees, forged documents, fictitious loans, and real estate deals.
The edifice is built on the silent theft of fixed deposits belonging to those least able to detect it -- the NRIs, away for years at a stretch, and elderly citizens, not very familiar with digital banking.
The Scale of Insider Fraud in Indian Banks
Government data tabled in the Rajya Sabha in early 2026, by Minister of State for Finance Pankaj Chaudhary, reveals that fraud cases, specifically involving bank employees, numbered 1,935 in FY25, down from 2,624 in FY21.
The number of such cases dropped further to 400 in the first half of FY26.
The decline in reported numbers, however, masks the complexity of such frauds.
An IIM Bangalore research paper, citing Reserve Bank of India data, says around 34 per cent of banking frauds are internal, attributable to junior and mid-level staff, questioning the integrity, credibility, survivability and processes of the banks.
Let"s get back to the NRI's case.
It"s not an isolated incident; it's the template of a criminal architecture that had been operating across branches of banks in different geographies for years.
How the Syndicate Operates
At stage one, a bank staff who has access to the system creates a loan against an NRI's term deposit, using forged documentation.
The original term deposit receipt (TDR) is never discharged. The lien mark exists in the system but the NRI customer is not aware of this.
At stage two, we see the play of an inter-branch rescue game.
Before the NRI returns, a second loan is raised in another branch -- this time, targeting a different depositor, and the proceeds are used to close the first loan.
The lien is lifted; evidence is buried, and new cheque books are issued from the second account -- again without the knowledge of the depositor.
At stage three, the syndicate comes in. When an internal investigation (triggered by a suspicious NRI customer's complaint) finally traces the money trail, it's found that a rogue employee is not acting alone.
It's a caucus of staff across multiple banks in the same city, rotating fraudulent loans to cover each other's tracks.
The proceeds are typically used for property deals. Whenever a curious customer asks questions, a new loan from yet another bank arrives to close the trail.
Such 'schemes' exploit the trust architecture of banking where branch staff are authorised to renew deposits, assist customers (NRIs or otherwise), and manage elderly account-holders' paperwork without adequate real-time oversight.
I am not weaving a story.
This has been playing out and documented across Indian banks in recent years.
Case Studies of Bank Employee Frauds
Chennai, 2025
The Central Crime Branch, a specialised, city-level police wing, responsible for investigating complex, organised, and high-profile crimes, arrested 49 bank employees in connection with 18 fraud cases involving forgery, misappropriation, and unauthorised withdrawals. Among the accused were clerks, cashiers, and managers.
Investigators found that bank staff had systematically targeted NRI fixed deposits, with Rs 8 crore siphoned off across multiple NRI accounts using forged signatures and cash vouchers.
In one case, the branch manager of a large new private bank fled the country after forging documents to steal Rs 7.5 crore from NRI investments; a Red Corner Notice was subsequently issued.
Mohali, 2025
The branch manager of a public sector bank was booked for securing a Rs 93 lakh loan against the fixed deposit of a retired teacher.
The fraud came to light when the victim made a routine branch visit -- six months after the unauthorised loan was raised.
The accused manager had gradually earned her trust before exploiting it.
He was working in conjunction with a real estate agent, confirming the cross-sector conduit that defines the more sophisticated syndicates.
Kota, 2025
A 26-year-old relationship manager of a very large new private bank was arrested for siphoning Rs 4.58 crore from over 110 accounts of 41 customers, the majority of which belonged to senior citizens.
She operated the fraud over three years (2020 to 2023), prematurely closing fixed deposits, activating overdraft facilities, and using digital banking to transfer funds to family members' accounts.
The diverted funds were invested in equity derivatives through platforms which buy and sell equities. The bank's internal audit detected the fraud.
Ahmedabad, 2025
The Enforcement Directorate arrested a PSB executive for fraudulently closing 127 term deposits, public provident fund accounts, senior citizen savings scheme accounts, and current accounts between May 2023 and July 2025, stealing Rs 16.10 crore.
Victims included senior citizens, deceased account holders, and minors. He was intercepted at a railway station attempting to flee the city.
Haryana, 2024
The manager at a Gurugram branch of the large new private bank (already mentioned) created fake accounts, forged signatures, and manipulated records to siphon Rs 16 crore from an NRI woman's savings account, accumulated over four years.
The fraud was discovered only when a new bank employee offered her better FD returns.
The customer wanted to shift money from a savings bank account to an FD to earn higher interest but there was no money in her account!
Systemic Vulnerabilities and Solutions
Before core banking solutions (CBS) became the backbone of the system, in the era of handwritten ledgers, incidence of fraud always left physical traces -- use of different ink, missing vouchers, inconsistent handwriting.
Every entry bore an employee's initials. Engineering large-scale frauds was structurally difficult. The migration to CBS transformed the game.
The CBS was designed to eliminate manual errors, enable real-time processing, and connect customers seamlessly across branches.
It succeeded on all these fronts. But it also has pockets of comfort for the insider-fraudster -- almost invisible within the complexity of daily transaction volumes.
The CBS formalised bank transactions but did not formalise oversight proportionally.
The system tracks who makes an entry but it doesn't ask why a particular entry is made.
Automated exception reports exist, but their review depends on human beings in an audit chain that is often under-resourced.
The RBI's revised Master Directions on Fraud Risk Management, issued in July 2024, mandated the creation of special committees of the Board for fraud oversight, deployment of Early Warning Systems (EWS), and a dedicated fraud risk management function at the general manager level or higher.
What the framework still lacks is a mandatory proactive notification system for depositors when any transaction occurs against their term deposit, including lien creation, premature closure, loan creation, or cheque book issuance.
For NRI and senior citizen accounts flagged as high trust-risk, a two-factor out-of-band confirmation (SMS/email directly to the depositor"s registered foreign number) before recording any lien, loan or premature closure addresses the vulnerability.
The most alarming dimension of the frauds perpetrated by insiders is their organised, multi-institutional character.
Individual rogue employees are manageable within the current framework but when a network of employees across competing banks coordinate, using each other's institutions as conduits to close loans, launder proceeds, and delay discovery, it's not easy to crack.
What happens when such frauds are detected? There have been cases of bank staff cooling their heels in jail but one can't miss the pattern: Detection is accidental, recovery is incomplete, and accountability is diluted -- often because banks prefer quiet settlement over criminal prosecution to protect institutional reputation.
Tamal Bandyopadhyay is an author and senior advisor to Jana Small Finance Bank Ltd. His latest book: Roller Coaster: An Affair with Banking.
Disclaimer: These are Tamal Bandyopadhyay's personal views.
Feature Presentation: Rajesh Alva/Rediff